The trend comes as the state pension age gradually increases and retirees seek greater certainty over their finances. Unlike lifetime annuities, which provide payments until death, fixed-term products allow individuals to reassess their retirement arrangements after several years without committing immediately to a lifelong income.
How Fixed-Term Annuities Help Bridge the Pension Gap
According to The Guardian, retirement specialists Standard Life and Canada Life have reported growing demand for fixed-term annuities, particularly among people looking to secure an income before their state pension begins.
These products convert pension savings into regular payments over an agreed period, typically 5 or 10 years. At the end of the term, the customer receives a predetermined lump sum, which can then be used according to their circumstances.
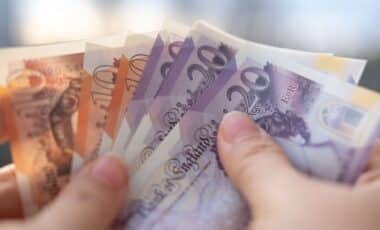
Standard Life provided an example involving a 62-year-old with a £100,000 pension pot. Under current terms, that individual could receive approximately £13,800 annually for five years, followed by a £50,000 lump sum when the agreement expires.
The annual payment exceeds the full new state pension of £12,548. Meanwhile, the state pension age is increasing from 66 to 67, with the transition scheduled for completion in April 2028. Standard Life’s research also found that 62 is the average age at which people would prefer to retire, leaving a potential gap between stopping work and qualifying for state pension payments.
Nick Flynn of Canada Life said customers were using fixed-term annuities to manage several financial commitments, including mortgage payments, school fees and the period before occupational pension benefits become available. He explained that the arrangements also give retirees time before deciding whether to enter pension drawdown or purchase a lifetime annuity.
Tax Changes and Widespread Confusion Influence Retirement Decisions
Changes to inheritance tax rules have also contributed to renewed interest in annuities. Announced by Rachel Reeves in the autumn 2024 budget, the measures are scheduled to take effect in April 2027.
Under the changes, unused defined contribution pension savings will no longer automatically remain outside inheritance tax calculations. Such funds could become taxable as part of an individual’s estate when the relevant threshold is exceeded. Yet understanding of annuities remains limited among prospective retirees.
According to Legal & General, a June 2026 survey of 2,000 UK adults aged 50 and over found that only 35% correctly identified lifetime annuities as providing guaranteed income for life.
The research also revealed differences between respondents. Some 43% of men recognised this feature, compared with 28% of women. Meanwhile, 30% of participants considered annuities too difficult to understand.
Another 17% believed that money held in an annuity would automatically be lost upon death, although certain contracts offer protection for spouses, partners or other beneficiaries. Legal & General explained that annuities can include guarantee periods and arrangements allowing payments to continue after the purchaser’s death.
The insurer also warned that these products are not suitable for everyone. Contracts generally cannot be altered or cancelled after the cooling-off period, while payments may lose purchasing power unless inflation protection is included. These restrictions remain relevant for retirees considering guaranteed income alongside flexibility in managing their pension savings.