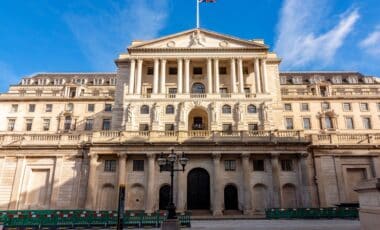
The Bank of England is expected to raise interest rates from 3.75% to 4% on Thursday, marking its first increase in borrowing costs since August 2023. The anticipated decision follows a rise in UK inflation, driven largely by higher fuel and energy prices linked to the conflict in the Middle East.
The announcement, scheduled for 12:00 GMT, comes after six consecutive meetings at which the Bank’s Monetary Policy Committee (MPC) kept rates unchanged. Economists widely expect a quarter-point increase, with attention also turning to what policymakers might signal about future decisions as households and businesses face higher borrowing costs.
Rising Energy Prices Put Pressure on the Bank of England
UK inflation reached 3.5% in September 2026, up from 3.1% in August and above the Bank of England’s 2% target. According to The Independent, the September figure was the highest recorded in 11 months, adding pressure on policymakers to respond.
Higher petrol and diesel prices have been a major contributor to the increase. The conflict involving Iran has also pushed up energy costs, with the effects feeding into prices across the UK economy.
Households face further pressure from domestic energy bills. Ofgem’s energy price cap increased by 3.6% for a typical household on 1 October, while a further 22% increase is forecast for January.
Ellie Henderson, an analyst at Investec, warned that sustained increases in energy costs could have wider consequences for inflation. “The longer energy prices remain elevated, the greater the risk that a temporary price shock becomes more permanent,” she said, suggesting that an interest rate increase could help manage that risk.
The Bank must also consider the wider economy. UK unemployment fell to 4.7% in the three months to August, its lowest level in more than a year, while economic output unexpectedly increased by 0.1% in August.
According to The Guardian‘s live business coverage on Thursday morning, financial markets were pricing in a 98% probability of an interest rate increase. Economists nevertheless differed over how committee members would vote, with forecasts ranging from a 6-3 split to an 8-1 majority.
Mortgage Borrowers Face Higher Repayments As Savers Await Changes
An increase in the Bank rate would affect mortgage borrowers differently depending on their agreements. Tracker mortgages respond directly to changes in the benchmark rate, while lenders determine whether to adjust their standard variable rates.
According to the BBC, approximately 510,000 tracker mortgage holders would face an immediate increase in repayments if the Bank raises rates by 0.25 percentage points.
Figures from UK Finance indicate that this would add around £31 to monthly repayments on a typical tracker mortgage. For approximately 470,000 borrowers on variable-rate deals, a similar increase would typically add £14 per month, depending on lenders’ decisions.
Fixed-rate borrowers would not see an immediate change to existing repayments. Those seeking new agreements, though, face borrowing costs considerably higher than those available five years ago.
Moneyfacts reported average two-year fixed mortgage rates of 5.96% on 4 November, compared with 5.99% for five-year agreements. Savers could benefit if banks and building societies increase the interest rates offered on deposits, although individual providers determine whether to pass on changes.