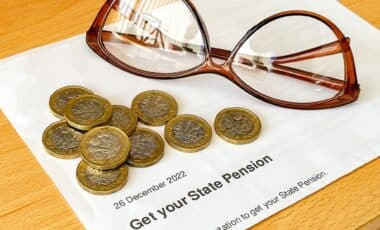
Some UK state pensioners could receive up to £1,930.40 from the Department for Work and Pensions (DWP) in October because of how the payment schedule falls during the month.
The higher total does not represent an increase in the weekly state pension rate. Instead, it comes from the timing of the regular four-week payment cycle, with some pensioners receiving two payments during a five-week month.
The arrangement mainly affects newer state pensioners who receive the maximum new State Pension amount and whose payment dates fall within the relevant schedule.
Some Pensioners Could Receive Two State Pension Payments
According to the Express, some younger state pensioners could receive two DWP payments in October 2026 because the month contains five Thursdays, affecting those whose payment schedule falls within that period.
State Pension payments are normally issued every four weeks rather than monthly, meaning the dates can sometimes create two payments within a single calendar month.
People who receive the maximum new State Pension amount could receive up to £965.20 for each four-week payment period. Two payments would therefore bring the October total to a maximum of £1,930.40.
The amount depends on individual entitlement, meaning not every pensioner will receive the maximum figure.
© Shutterstock
National Insurance Numbers Determine Payment Dates
According to the DWP, state pension payment days are usually linked to the final two digits of a person’s National Insurance number.
Those with National Insurance numbers ending between 40 and 59 are normally paid on Wednesdays. Other groups have different payment schedules depending on their final digits.
The payment date system means not every state pensioner will receive two payments in October. The timing depends on when their regular four-week payment cycle falls.
Pensioners with incomplete National Insurance records may receive less than the maximum amount, with their payment calculated based on their individual contribution history.
Who Can Receive The Maximum New State Pension Amount
People who reached state pension age after April 2016 are covered by the new State Pension system.
A full National Insurance record is required to receive the maximum weekly amount. The current maximum payment for these pensioners is £241.30 per week, which equals £12,547 per year when calculated across regular payments.
The age of the oldest person who started receiving the new State Pension is now around 77, depending on their date of birth.
Older pensioners and newer retirees can both receive state pension payments in October according to their normal payment arrangements, but the maximum figures differ depending on their circumstances.
Tax Rules Could Affect Some Pensioners
Although the annual basic State Pension amount for a maximum new State Pension recipient is below the standard personal tax allowance, other sources of income may affect whether someone pays tax.
Income from savings, employment, or property rental could push a person above the tax threshold.
Future changes to pension taxation have also been discussed by the government. Plans announced by the Chancellor suggested that some pensioners above the personal allowance may not pay tax on their State Pension if they have no other income.
Further details on how those arrangements would operate are expected to be clarified after the upcoming Budget.
Payment Timing Creates Temporary October Difference
The October payment situation is a result of the calendar rather than a permanent change to pension rates.
State pension recipients should continue checking their usual payment dates and the amount shown by the DWP, as individual circumstances vary depending on National Insurance records and entitlement levels.
For eligible pensioners receiving the full new State Pension rate, two four-week payments in October 2026 could total up to £1,930.40.